Us humans like to think we're very rational creatures, but most of what drives us runs a lot deeper than logic. Fear, greed, and pride are biological, hardwired into us long before money ever existed. And that's the problem. Our brains simply weren't built for the modern financial world. They were built to survive on the savanna, not to figure out how the next thirty years are going to play out. Instant gratification is not just some character flaw. It was a survival trait. For most of the last two hundred thousand years, humans spent almost all of their time and energy just trying to make it to tomorrow. There was no such thing as retirement. There was no compound interest. There was no delayed gratification. There was just food, shelter, and threats to avoid.
For most of human history, this kind of privilege, being able to actually save money and let it grow over decades instead of spending every waking hour trying to survive, belonged to a handful of people. Kings, nobles, whoever sat at the top. Everyone else was just trying to get by. Now, most people in the developed world have that same privilege. The problem is that the same instincts that kept us alive do not just disappear because our basic needs are met. And that mismatch is where a lot of financial mistakes start.
The Evolutionary Mismatch
The human brain was not shaped in a classroom or a boardroom. It was shaped in small tribes, in unpredictable environments, where the stakes were often life or death. Our brains evolved to react to scarcity, discomfort, and immediate physical risk. That is the environment that built us.
Compare that to retirement planning. In banking terms, you could say we have a duration mismatch. Our brains are wired for short, tangible, immediate things: find food, avoid danger, survive today. Retirement is the opposite of all that. It is abstract, it is decades away, and there is no immediate feedback telling you whether you are doing it right.
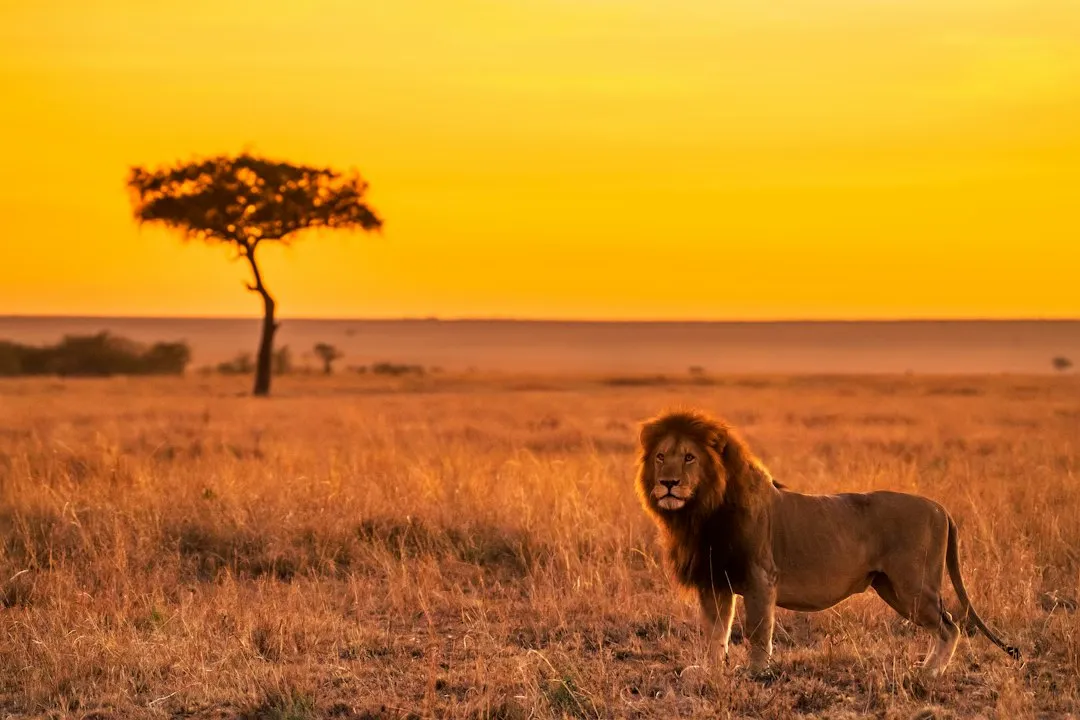
Here is the problem. Your brain cannot always tell the difference between a lion chasing you and your account balance dropping 20%. Both trigger the same fear response. The threat feels just as real, even though one might actually kill you and the other is just part of how markets work. A 20% drop does not necessarily mean something has gone wrong. It might just mean the market is doing what markets have always done. But in that moment, your brain does not always know the difference.
This is not a personal failing. It is old programming trying to run in a brand new environment. And unlike a computer, you cannot just update human biology from one operating system to the next. Our wiring does not upgrade itself. If anything is going to change, it has to be us, learning to recognize when our instincts are helping and when they are working against us, and building habits and systems that work around the wiring instead of fighting it.
Why Investing Feels So Hard
I can't tell you how many phone calls I got in March 2020. And honestly, for good reason. Within just 33 days, the S&P 500 plunged about 34%, the fastest bear market on record. Nobody can tell me they didn't wonder, at least for a moment, if the world was ending. We have the benefit of hindsight now. In that moment, nobody had it.
That fear comes from the same wiring we just talked about. And here's the part that surprises a lot of people: it doesn't go away just because life gets safer. Most of us aren't worried about lions anymore. Our basic needs are met. You'd think that would make us calmer. But our brains don't really work that way.
A 2018 study by Harvard researchers David Levari, Daniel Gilbert, and their colleagues found something fascinating. When threatening faces became rare, participants began to see neutral faces as threatening. In versions of the experiment, the effect held even when people were warned about it ahead of time and even when they were paid to resist it. In other words, when real threats become rare, the brain doesn't relax. It just lowers the bar for what counts as a threat.
That's what can happen with our money. When there's no lion, a 20% drop in your account can start to feel like one. Your brain says something is wrong, do something, get out.
And that's where the trouble starts. Fear tends to push people to sell after the market has already dropped. Then, once things recover and the headlines turn positive, relief (or excitement) pulls them back in. They end up doing the exact opposite of what they're supposed to do: sell low, buy high. Nobody sets out to do that, but it's exactly what our wiring nudges us toward.
Looking back at March 2020, it's easy to think, "Well, of course it came back." That's hindsight talking. And hindsight has a sneaky side effect. It makes us think we'd stay calm next time, that we'd see it coming, or at least sit tight. But the next drop won't come with a label telling you it's temporary. It will feel just as real as the last one. That's why investing feels so hard. It's not that people don't know what they're supposed to do. It's that their brain is shouting the opposite.
The Problem With Long Term Thinking
Retirement planning asks us to do something that goes completely against how we're wired. It asks us to give up something now for a benefit that might be twenty or thirty years away. For most of human history, that would have made no sense. If you had food, you ate it. If you had a chance to get ahead today, you took it, because tomorrow was never guaranteed.
Today, most of us live in a world where our basic needs are met and there isn't any immediate danger. We actually have the ability to think long term. But having the ability and having the instinct are two very different things.
Part of the reason it's so hard has to do with how we think about our future selves. UCLA psychologist Hal Hershfield has spent years studying this, and his research suggests that when people think about themselves far in the future, it can feel a lot like thinking about a different person. In one study, his team used brain scans and found that when people described themselves ten years from now, their brain activity looked different from when they described themselves today, and more similar to when they talked about someone else entirely.
Think about what that means for saving. If your future self feels like a stranger, then putting money into a retirement account can feel a lot like handing your paycheck to someone you've never met. Of course that's hard. Your brain is asking, "Why would I give my money to that guy?"
That's really the heart of the problem with long term thinking. It's not that people don't care about their future. It's that the future version of themselves doesn't feel real enough to compete with what they want right now. And when the person you're saving for feels like a stranger, today will win almost every time.
How Social Instincts Affect Money
For most of human history, being part of the tribe meant survival. Getting separated from the group, or worse, cast out of it, could mean death. So we evolved to pay very close attention to what everyone around us was doing. If the people around you suddenly started running, you ran too and asked questions later. The ones who stopped to think it through didn't always get the chance to pass on their genes.
That instinct is still with us, and it shows up in our money in a big way.
Look at almost any bubble or mania. The dot-com boom in the late 1990s. The housing run up in the mid 2000s. Crypto and meme stocks more recently. The details are different every time, but the feeling is the same. Everyone around you seems to be making easy money, your neighbor is talking about it at the cookout, and sitting on the sidelines starts to feel almost physically uncomfortable. Nobody wants to be the one left behind. And it works the same way in reverse. When everyone starts heading for the exits, staying put can feel like standing still while the rest of the tribe runs from the lion.
For people getting close to retirement, though, the herd usually isn't the internet. It's much closer to home. It's the neighbor who claimed Social Security at 62. The brother-in-law with the hot stock tip. The coworker who retired early and seems to be doing great. The friend whose advisor has them in something they can't stop talking about.
None of those people are necessarily wrong. The problem is that their situation might look nothing like yours. Different income, different savings, different health, different goals, different taxes. A decision that made sense for your neighbor could create real problems for you. But our wiring doesn't care about any of that. It just sees the tribe moving in one direction and wants to follow.
Some of the biggest retirement decisions people make, like when to claim Social Security, when to retire, or how to invest, are permanent or close to it. Those are exactly the decisions where following the crowd can be the most costly, and where it pays to slow down and ask whether the crowd's answer is actually your answer.
Why Compound Growth Feels Invisible
Our ancestors lived in a straight line world. If you walked twice as far, it took twice as long. If you gathered twice as many berries, you had twice as much food. Almost nothing they dealt with grew on top of itself, so our brains never really developed a feel for it.
That's a problem, because compound growth is anything but a straight line.
Here's a classic way to think about it. Would you rather have $1 million today, or a penny that doubles every day for 30 days? Most people take the million. And for a while, that looks like the right call. After two weeks, the penny is worth about $82. By day 20, it's around $5,200. Not bad, but nowhere close. Then something happens. By day 30, that penny has grown to roughly $5.4 million. And half of that shows up on the very last day.
That's what makes compounding so hard to appreciate. For a long time, it looks like nothing is happening. The early growth feels small, almost pointless. Then the curve bends, and most of the growth shows up at the end. Our brains are built to judge things by what we can see right now, and right now, compounding rarely looks impressive.
A lot of people think of compounding as a young person's game. Start early, let it grow, and by retirement the work is done. But compounding doesn't stop when the paychecks do. Someone retiring in their early 60s could easily have a 25 or 30 year time horizon. That's a long runway, and some of the biggest growth can still be ahead.
It also works in both directions. Inflation compounds. Taxes compound. At 3% inflation, prices roughly double in about 24 years, which means the same lifestyle could cost twice as much by the end of a long retirement. A decision that looks small today, like paying an extra half percent in taxes, can quietly add up to something meaningful over two or three decades.
The penny doesn't feel like much on day 14. Neither do most of the decisions that end up mattering most.
What We Can Do About It
In Homer's Odyssey, Odysseus has to sail past the Sirens, whose song was said to be so irresistible that sailors would steer straight into the rocks just to get closer. Odysseus wants to hear it, but he also knows he won't be able to resist it. So before they get close, he has his crew plug their ears with beeswax, tie him to the mast, and ignore anything he says until they're safely past.
He doesn't rely on willpower. He knows exactly how his brain is going to react in the moment, so he builds a system ahead of time that keeps him from acting on it.
That's really the answer to everything we've talked about. We can't rewire two hundred thousand years of instinct. But we can plan around it. A few ways that might look:
Have a plan for downturns before they happen. Morgan Housel has a great way of putting it in The Psychology of Money: volatility is a fee, not a fine. A fine is a punishment for doing something wrong. A fee is the price of admission for something valuable. Our brains tend to treat every drop like a fine, but more often than not, it's simply the fee for being invested. Fear is at its loudest when the market drops, so that's the worst time to be making decisions from scratch. One common approach is keeping a few years of planned withdrawals in cash or more conservative investments, so you're not forced to sell stocks after a drop just to pay the bills. When you know where next year's income is coming from, a 20% decline can be a lot easier to sit through.
Make the future concrete. If your future self feels like a stranger, get to know them. Write out what retirement actually looks like. Where you'll live, how you'll spend your days, what you want to do while you're healthy enough to do it. And wherever possible, automate. The fewer times you have to make the same decision, the fewer chances your wiring has to talk you out of it.
Base decisions on your plan, not your neighbor's. When the herd starts moving, the question isn't "what is everyone else doing?" It's "does this fit my plan?" If it's not in the plan, it doesn't happen on a whim.
Pay attention to the quiet stuff. Costs, taxes, and inflation don't make headlines, but they compound year after year. Small decisions, made consistently over a long retirement, can matter more than the big dramatic ones.
Work with someone who can be your crew. Even Odysseus needed someone to tie the knots. In my opinion, a good advisor is maybe 10% investment manager and 90% coach, money therapist, guide, and everything in between. The investments matter, but a lot of the value comes from helping people stick to the plan when their brain is screaming at them to do the opposite.
Conclusion
We like to think of ourselves as rational, but most of our financial instincts were shaped long before money even existed. Our brains were built for the savanna. They were built to run from lions, stick with the tribe, and eat today because tomorrow wasn't guaranteed. Modern finance asks those same brains to sit still through a 20% drop, save for a future self that feels like a stranger, ignore what the neighbors are doing, and trust a penny that doesn't look like much until day 30.
That's a lot to ask. So if investing has ever felt harder than it should, you're not doing it wrong. You're human.
The good news is you don't have to win the fight against your own wiring. You just have to plan around it. Odysseus didn't sail past the Sirens because he was stronger than everyone else. He made it because he knew himself well enough to tie himself to the mast before the music started.
The goal isn't to have perfect instincts. Nobody does. The goal is to have a plan that's built for the moments when your instincts will be at their worst.
If you're getting close to retirement and want help building that kind of plan, Kelda Wealth works with Ohio and Midwest families to organize the pieces and make decisions they can feel confident about, even when their brain is telling them otherwise.
Levari, D. E., Gilbert, D. T., Wilson, T. D., et al. "Prevalence-induced concept change in human judgment." Science, 2018. doi.org/10.1126/science.aap8731
Ersner-Hershfield, H., Wimmer, G. E., and Knutson, B. "Saving for the future self: Neural measures of future self-continuity predict temporal discounting." Social Cognitive and Affective Neuroscience, 2009. See also: The stranger within: Connecting with our future selves (UCLA Health)
Housel, Morgan. The Psychology of Money. Harriman House, 2020.
S&P 500 index data, February 19 to March 23, 2020. Marotta on Money